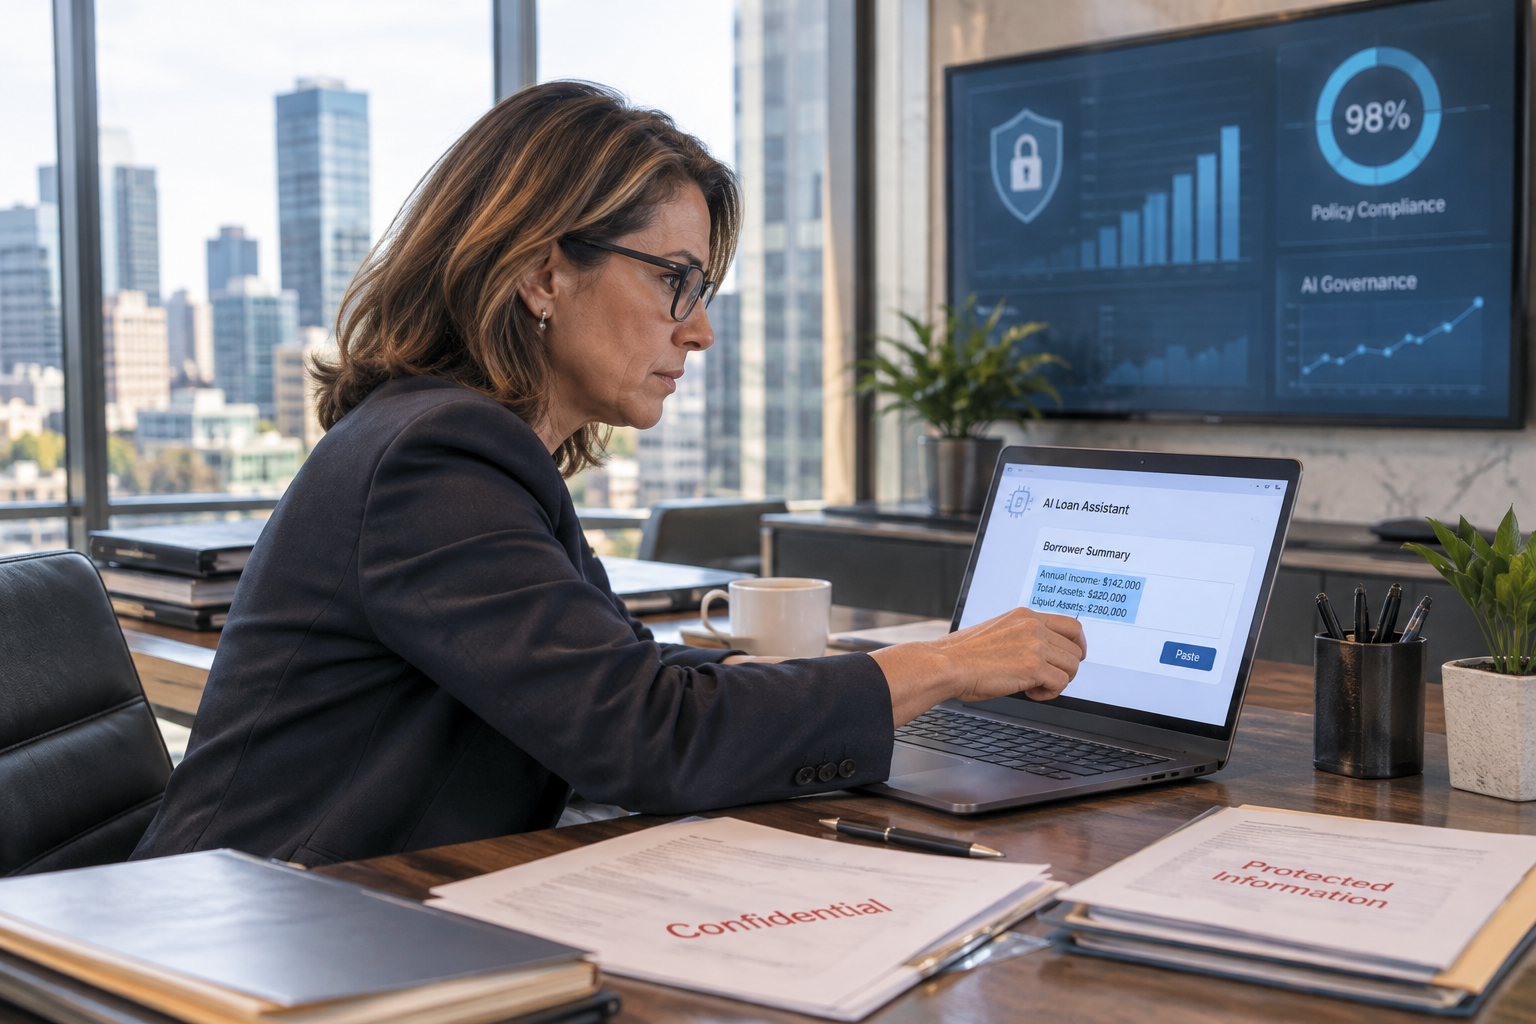
Illustrative scenario. A loan officer pastes a borrower’s income and asset summary into a free AI tool to draft a narrative. The tool returns a usable draft, but the borrower’s information has gone to a system the firm did not choose and may not be able to audit.
The firm needs to account for that use just as it accounts for other systems receiving protected information. Tools adopted outside its review process can be missing from those records.
IBM’s 2025 Cost of a Data Breach Report studied 600 organizations that experienced breaches between March 2024 and February 2025. One in five of those organizations reported a breach linked to shadow AI, meaning AI used without employer approval or oversight. Organizations with high levels of shadow AI had average breach costs $670,000 higher than those with low levels or none. Among the breached organizations studied, 63% had no AI governance policy or were still developing one. IBM report findings
Mortgage firms handle Social Security numbers, income documents, bank statements, and underwriting information. Staff need clear rules for using AI with any of those materials.
Set the rules for loan work
- Find the tools already in use. Include personal AI accounts used for work, browser extensions, AI features in loan origination systems (LOS), customer relationship management (CRM) software, and document tools, plus scripts connected to external models.
- Write the rule on one page. Allow public information, published material, and generic process questions. Keep borrower-identifying information, income and asset details, underwriting decisions, and pricing exceptions out of unapproved tools.
- Teach the prompt. Use examples from borrower narratives and loan documents. Show what staff can submit, what must be removed, and when they need approval.
Connect AI, device, and vendor inventories
The FTC Safeguards Rule applies to financial institutions under FTC jurisdiction, including covered nonbank mortgage lenders, brokers, and account servicers—not automatically every lender. It requires safeguards for customer information and oversight of service providers. Link device, vendor, and AI inventories to support that work.
Update the records when tools or loan workflows change.
Put approved uses in writing and resolve exceptions before staff submit borrower information.